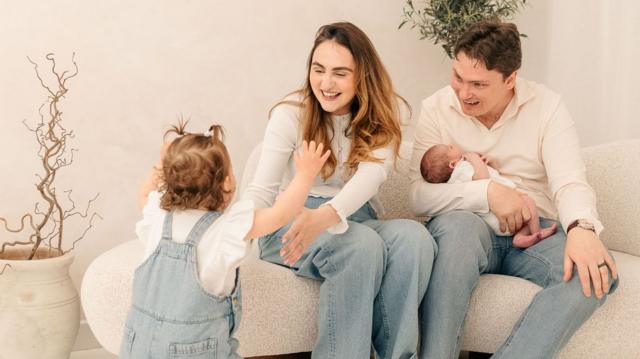

Photo credit: Richard Brain
Richard and Caitlin Brain’s two children are just one and a half years and five months old, yet Mum and Dad have already opened pension accounts for them.
The Brainys, who live in Swansea in South Wales, pay in £50 (66 dollars) a month for each child.
Under current UK private pension fund rules, the children will not be able to access this money until they reach the age of 57.
The eldest child will have to wait until 2082, and the youngest until 2083.
Despite such a long wait, 30-year-old Richard is convinced that he and 28-year-old Caitlin are doing the right thing.
“Contributing to their pensions means we can help shape their future far beyond our own lifetimes. And this money will have decades to grow,” he says.
“We don’t very often
The couple believe this combines the benefits of both approaches: ISAs can help their children pay for university, start a business or make a deposit on a home, whilst pensions are designed to provide financial security much later in life.
By contributing a total of £220 ($292) a month to their children’s funds, as well as £200 ($265) to their own private pensions and savings, the couple say they now have to live more frugally than before.
“We’re not living below the poverty line, but investing this money means we have to cut back a little on certain things,” says Richard.
“We don’t go to restaurants as often as we used to, which is a bit of a shame because we love a good meal,” he admits.
And we don’t spend as much on each other for birthdays and Christmas, so that
Another firm, Fidelity, says that since December 2023, the number of such accounts has more than tripled.
For some parents, the chance to give their children a head start on saving for their pensions is a powerful incentive, but how do the children themselves feel about not being able to access this money for potentially 50 years or even longer?
Fifteen-year-old Hugo Thompson from Manchester seems to be quite comfortable with this.
His parents, who work in the financial sector, have been paying the maximum possible amounts into his junior SIPP for the past 10 years.
“Investing money means I might have an advantage when I get older,” he says.
“So I won’t need to put in as much of my own money! I want to retire before the state pension age, so all of this will help,” he adds
“By the time I retire, this amount could grow to around £135,000 ($179,171). That’s the real power of starting early: relatively small sums have an extremely long time to grow,” adds the expert.
It is not only British parents who are opening long-term investment accounts for their children.
In July this year, US President Donald Trump launched a new retirement investment scheme for children called Trump Accounts.
Family, friends and employers can contribute up to $5,000 a year per child.
The difference from the British system is that children can access these funds once they turn 18, although withdrawals are subject to tax and may incur a 10 per cent penalty if made before the age of 59 and a half.