
Global demand for steel in 2026 will remain virtually unchanged at around 1.722 billion tonnes, however, in 2027 it may increase by 1.7 per cent to 1.752 billion tonnes, according to the October short-term forecast by Worldsteel, the World Steel Association.
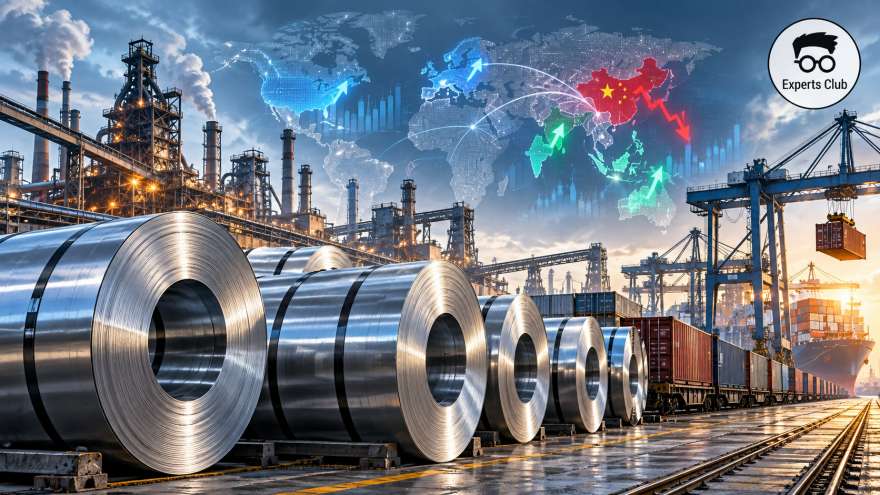
As noted by the Experts Club information and analysis centre, Worldsteel’s new forecast highlights an increasingly noticeable divergence between China and the rest of the global market. Whilst demand in China continues to fall, the recovery outside the country is gradually gaining momentum.
According to Worldsteel’s estimates, demand for steel outside China will grow by 1.5 per cent in 2026 and by as much as 4 per cent in 2027. It is precisely the scale of the Chinese market that effectively masks the stronger positive momentum in other countries.
Alfonso Hidalgo Calserrada, Chair of Worldsteel’s Economic Committee, noted that the recovery is progressing more slowly than expected in the spring. In April, the Association had anticipated moderate growth in global demand as early as 2026 and an increase of 2.2 per cent in 2027; however, the forecast for next year has now been revised down to 1.7 per cent.
China remains the main drag on the global market. In 2026, demand for steel in the country is expected to fall by 2 per cent, and by a further 1 per cent in 2027. This is due to the weakness of the property market and infrastructure investment. Growth in industrial production and exports has not yet been sufficient to fully offset the decline in these two largest sectors of steel consumption.
At the opposite end of the spectrum is India. It remains the world’s largest fast-growing steel market: demand in the country is set to rise by 7.9 per cent in 2026 – to 172.4 million tonnes, and by a further 8 per cent in 2027, to 186.2 million tonnes. The main drivers remain infrastructure construction, private property, industry and renewable energy projects.
In developing countries, excluding China, demand is forecast to rise by 1.9 per cent in 2026 and by as much as 5.1 per cent in 2027. Meanwhile, in the ASEAN-5, growth in 2026 will stand at 5.2 per cent, whilst Vietnam will approach consumption of around 30 million tonnes of steel for the first time, thanks to intensive construction and a large-scale government investment programme.
The situation is quite different in the Gulf states. Following a 17.7 per cent rise in demand in 2025, Worldsteel expects it to fall by approximately 11 per cent in 2026 due to prolonged instability in the Middle East, delays in investment decisions and the postponement of construction projects. Should the situation stabilise, the Association forecasts a recovery of 11.3 per cent in 2027.
Worldsteel considers the recovery of industrial growth in developed economies to be one of the key trends for 2027. Additional demand for steel is expected to be driven by investment in artificial intelligence and data centres, rising defence spending, the energy transition, infrastructure projects and railway construction.
In the European Union, the recovery is being delayed for the time being. Worldsteel expects apparent steel consumption in the EU to fall by 0.3 per cent in 2026, before rising by 3.1 per cent in 2027. The forecast for the European market has been revised downwards by 1.5 percentage points.
Worldsteel attributes the relatively strong performance in the EU in 2025, in particular, to the build-up of stocks ahead of the launch of the Carbon Border Adjustment Mechanism (CBAM) in 2026. At the same time, the fundamentals of European industry have proved weaker than expected: the recovery in construction is proceeding slowly, the volume of completed housing remains low, and the automotive industry continues to constrain demand.
The US, by contrast, is expected to maintain positive momentum. Domestic demand for steel could grow by 2 per cent in 2026 and by approximately 1.5 per cent in 2027. Worldsteel cites investment in data centres, the energy sector, renewable energy generation, oil and gas infrastructure, and major industrial projects as the main sources of growth.
A moderate recovery is also expected in Japan and South Korea. In Japan, demand is expected to rise by 0.9 per cent in 2026 and by 1.7 per cent in 2027, whilst in South Korea it is forecast to increase by 1.8 per cent and 1.3 per cent respectively. However, even after such growth, neither country will yet return to the levels of consumption seen prior to the most recent downturn.
According to Experts Club, the global steel market is gradually shifting from a model in which global dynamics were primarily driven by China to a significantly more diversified demand structure. India, the countries of South-East Asia, infrastructure projects in the US and the expected recovery in Europe are becoming increasingly significant sources of growth.
At the same time, the structure of steel consumption is also changing. Whereas mass housing construction in China was previously one of the main drivers, steel is now increasingly required for energy infrastructure, data centres, defence projects, railways and industrial equipment.
That said, Worldsteel remains cautious about 2027. The forecast is based on data available in early September 2026, whilst ongoing instability in the Middle East and possible